Client Login Start a conversation
What we do

Planning that starts with a conversation.

Retirement brings new questions about income, taxes, health care, and family. We help you work through them with a customized plan, an investment approach built around that plan, and regular reviews to keep it current.

Start the conversation

Three parts of one plan.

We build the plan around you, invest according to the plan, and review it as your life changes.

01 Planning

Your complete financial picture.

We start by learning your goals, your concerns, and your full financial situation. From there, we build a customized plan using a cash flow analysis based on conservative assumptions that we agree on together. We also calculate your hurdle rate, which is the rate of return your plan needs under those assumptions. It's a planning tool, not a promise, and it helps us identify how much investment risk your plan may call for.

Understanding your goals Building the plan Retirement income Taxes Insurance Ongoing maintenance
02 Investing

Our Invest and Protect approach.

Invest and Protect is designed to pursue growth when markets are favorable and also to have a plan in place to protect in downturns. We aim to take only as much risk as your plan calls for, and we manage your investments in the context of your goals, not in isolation. All investing involves risk, including the possible loss of principal.

03 Reviewing

A plan that keeps pace with your life.

Most clients meet with us about every six months, and we meet more often when life calls for it. Some reviews are a five-minute phone call. Others take an hour and a half. We look at what's changed, check the plan, and talk through decisions such as taxes, whether a Roth conversion makes sense, and whether your estate documents are current. Most importantly we update your financial plan to make sure you stay on track. Our goal for you is for your money to last as long as you do. We consider the review process the most important part of our relationship with you.

One team across your financial life.

Select a service to see how it fits into your plan.

Financial planning

What this is

A customized plan built on your full financial picture, including income, expenses, savings, and goals. We use a cash flow analysis with conservative assumptions and update it as things change.

Why it matters

Decisions near and in retirement connect to one another. A plan lets us look at them together instead of one at a time.

A relationship built on clarity from the first conversation.

Getting started shouldn't feel like a leap. Here's exactly what to expect.

01

Your first two meetings

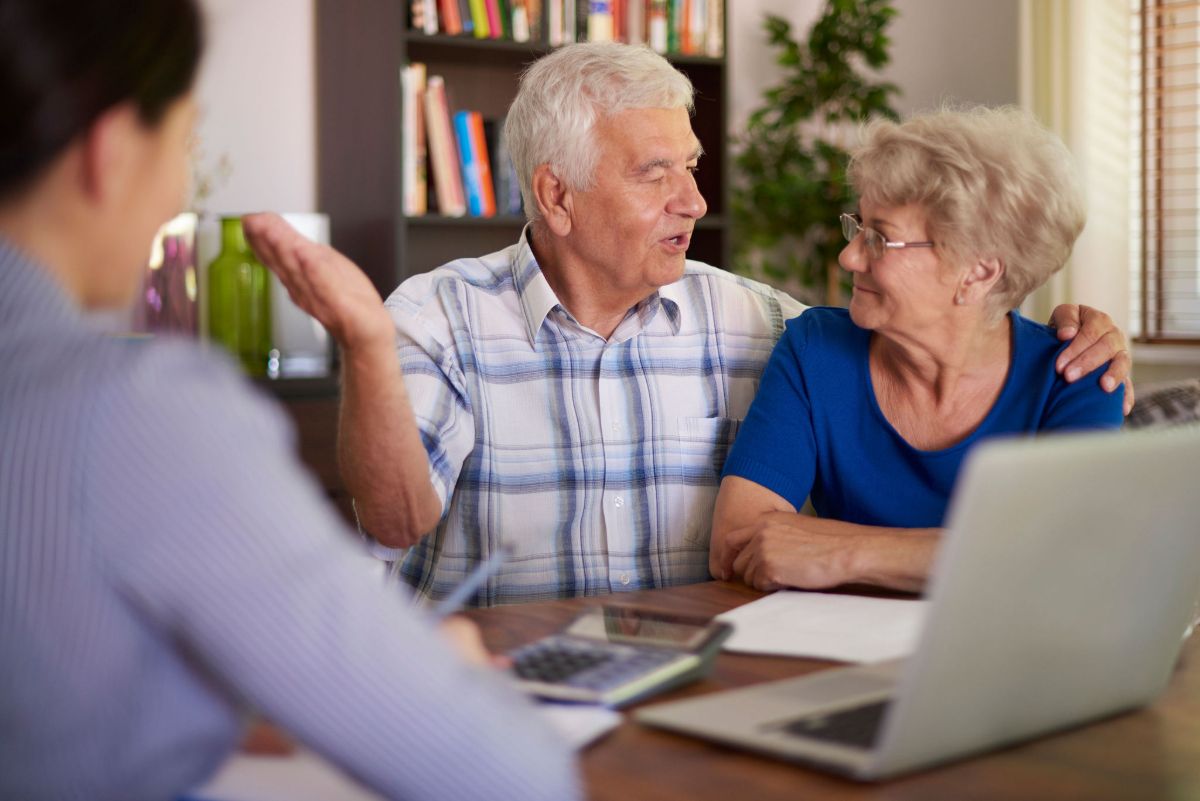
In the first meeting, we talk about your goals, your concerns, and your complete financial situation. Between meetings, we build your customized plan. In the second meeting, we walk you through the plan and our Invest and Protect approach, and we review all costs openly. There's no charge and no obligation. If it isn't the right fit, we'll part friends.

02

What meetings look like

Every meeting starts with you. We ask about your goals, objectives, and concerns, and what has changed in your life, before we talk about what has changed in your accounts. You choose where we meet: in our office, by Zoom, or by phone.

03

How we communicate

When you call our office, a real person answers. You can reach us by phone, by email, or in person.

Frequently asked questions

Questions about the plan.

Last reviewed: October 2026

Have a question that isn't here? Start with a conversation.

How do I create and maintain a financial plan?

A financial plan starts with your goals, then maps your income, spending, savings, investments, taxes, insurance, and estate documents against them. After it is built, review it at least once a year and after major life changes, because a plan only works when it reflects your current situation.

Where should my retirement income come from?

Retirement income usually comes from a mix of Social Security, pensions, withdrawals from savings and investment accounts, and sometimes part-time work or rental income. The order you draw from taxable, tax-deferred, and Roth accounts can affect your taxes, so it helps to plan withdrawals as a sequence.

How can I reduce my income taxes in retirement?

Retirees often focus on three things: which accounts they withdraw from, when they take income, and how they give. Common tools include Roth conversions, qualified charitable distributions, coordinating Social Security timing, and holding investments in the account types where they are taxed most favorably. The right mix depends on your situation, so involve your CPA.

Should I consider a Roth conversion?

A Roth conversion moves money from a traditional IRA or similar pre-tax account into a Roth IRA. You pay income tax on the amount converted in the year you convert, and after that, qualified withdrawals can be tax-free. Whether it makes sense depends on your current and expected future tax brackets, how you will pay the tax, and your timeline.

How can I prepare my portfolio for a market downturn?

No strategy can fully protect investments from a downturn or a bear market, but you can plan for one. Common steps include diversifying, keeping enough cash or stable assets to cover near-term spending, matching risk to your timeline, reviewing the plan regularly and most importantly having a plan in place to strive to Protect your Investments in the event of a Market Downturn. Our Invest and Protect approach is designed to account for market downturns, and of course all investing involves risk.

Should my portfolio get more conservative as I get older?

Often, but not automatically. The most important goal is to invest to meet or exceed the minimum rate of return you need to keep pace with the customized financial plan we will develop with you. Many people shift toward more stability as they near and enter retirement, because they have less time to recover from a downturn and they begin drawing income. The right mix depends on your income needs, your other sources of income, your time horizon, and how much decline you can tolerate.

Do I need long-term care insurance?

Not everyone does. Medicare doesn't cover most long-term custodial care, so people generally choose among buying long-term care coverage, setting aside assets to pay for care themselves, or combining both. The right choice depends on your assets, your health, your family, and how you would want care provided.

Do I need life insurance?

You need life insurance if someone would face financial hardship if you died, such as a spouse who depends on your income, children, a business partner, or debts that would pass to others. Many retirees need less or none if their assets cover their family's needs, though some keep coverage for estate or legacy goals.

This information is general and educational. It is not personalized investment, tax, or legal advice. Figures and rules shown reflect 2026 and can change. Investing involves risk, including the possible loss of principal.

Let's talk about what you want your money to do.

Start a conversation
Powered by
RFG Advisory BNY Pershing

We work with RFG Advisory for technology and operational support. Client accounts are held at Pershing.

Start a Conversation